Globalaw - Home
ContactMember Login
Our social network
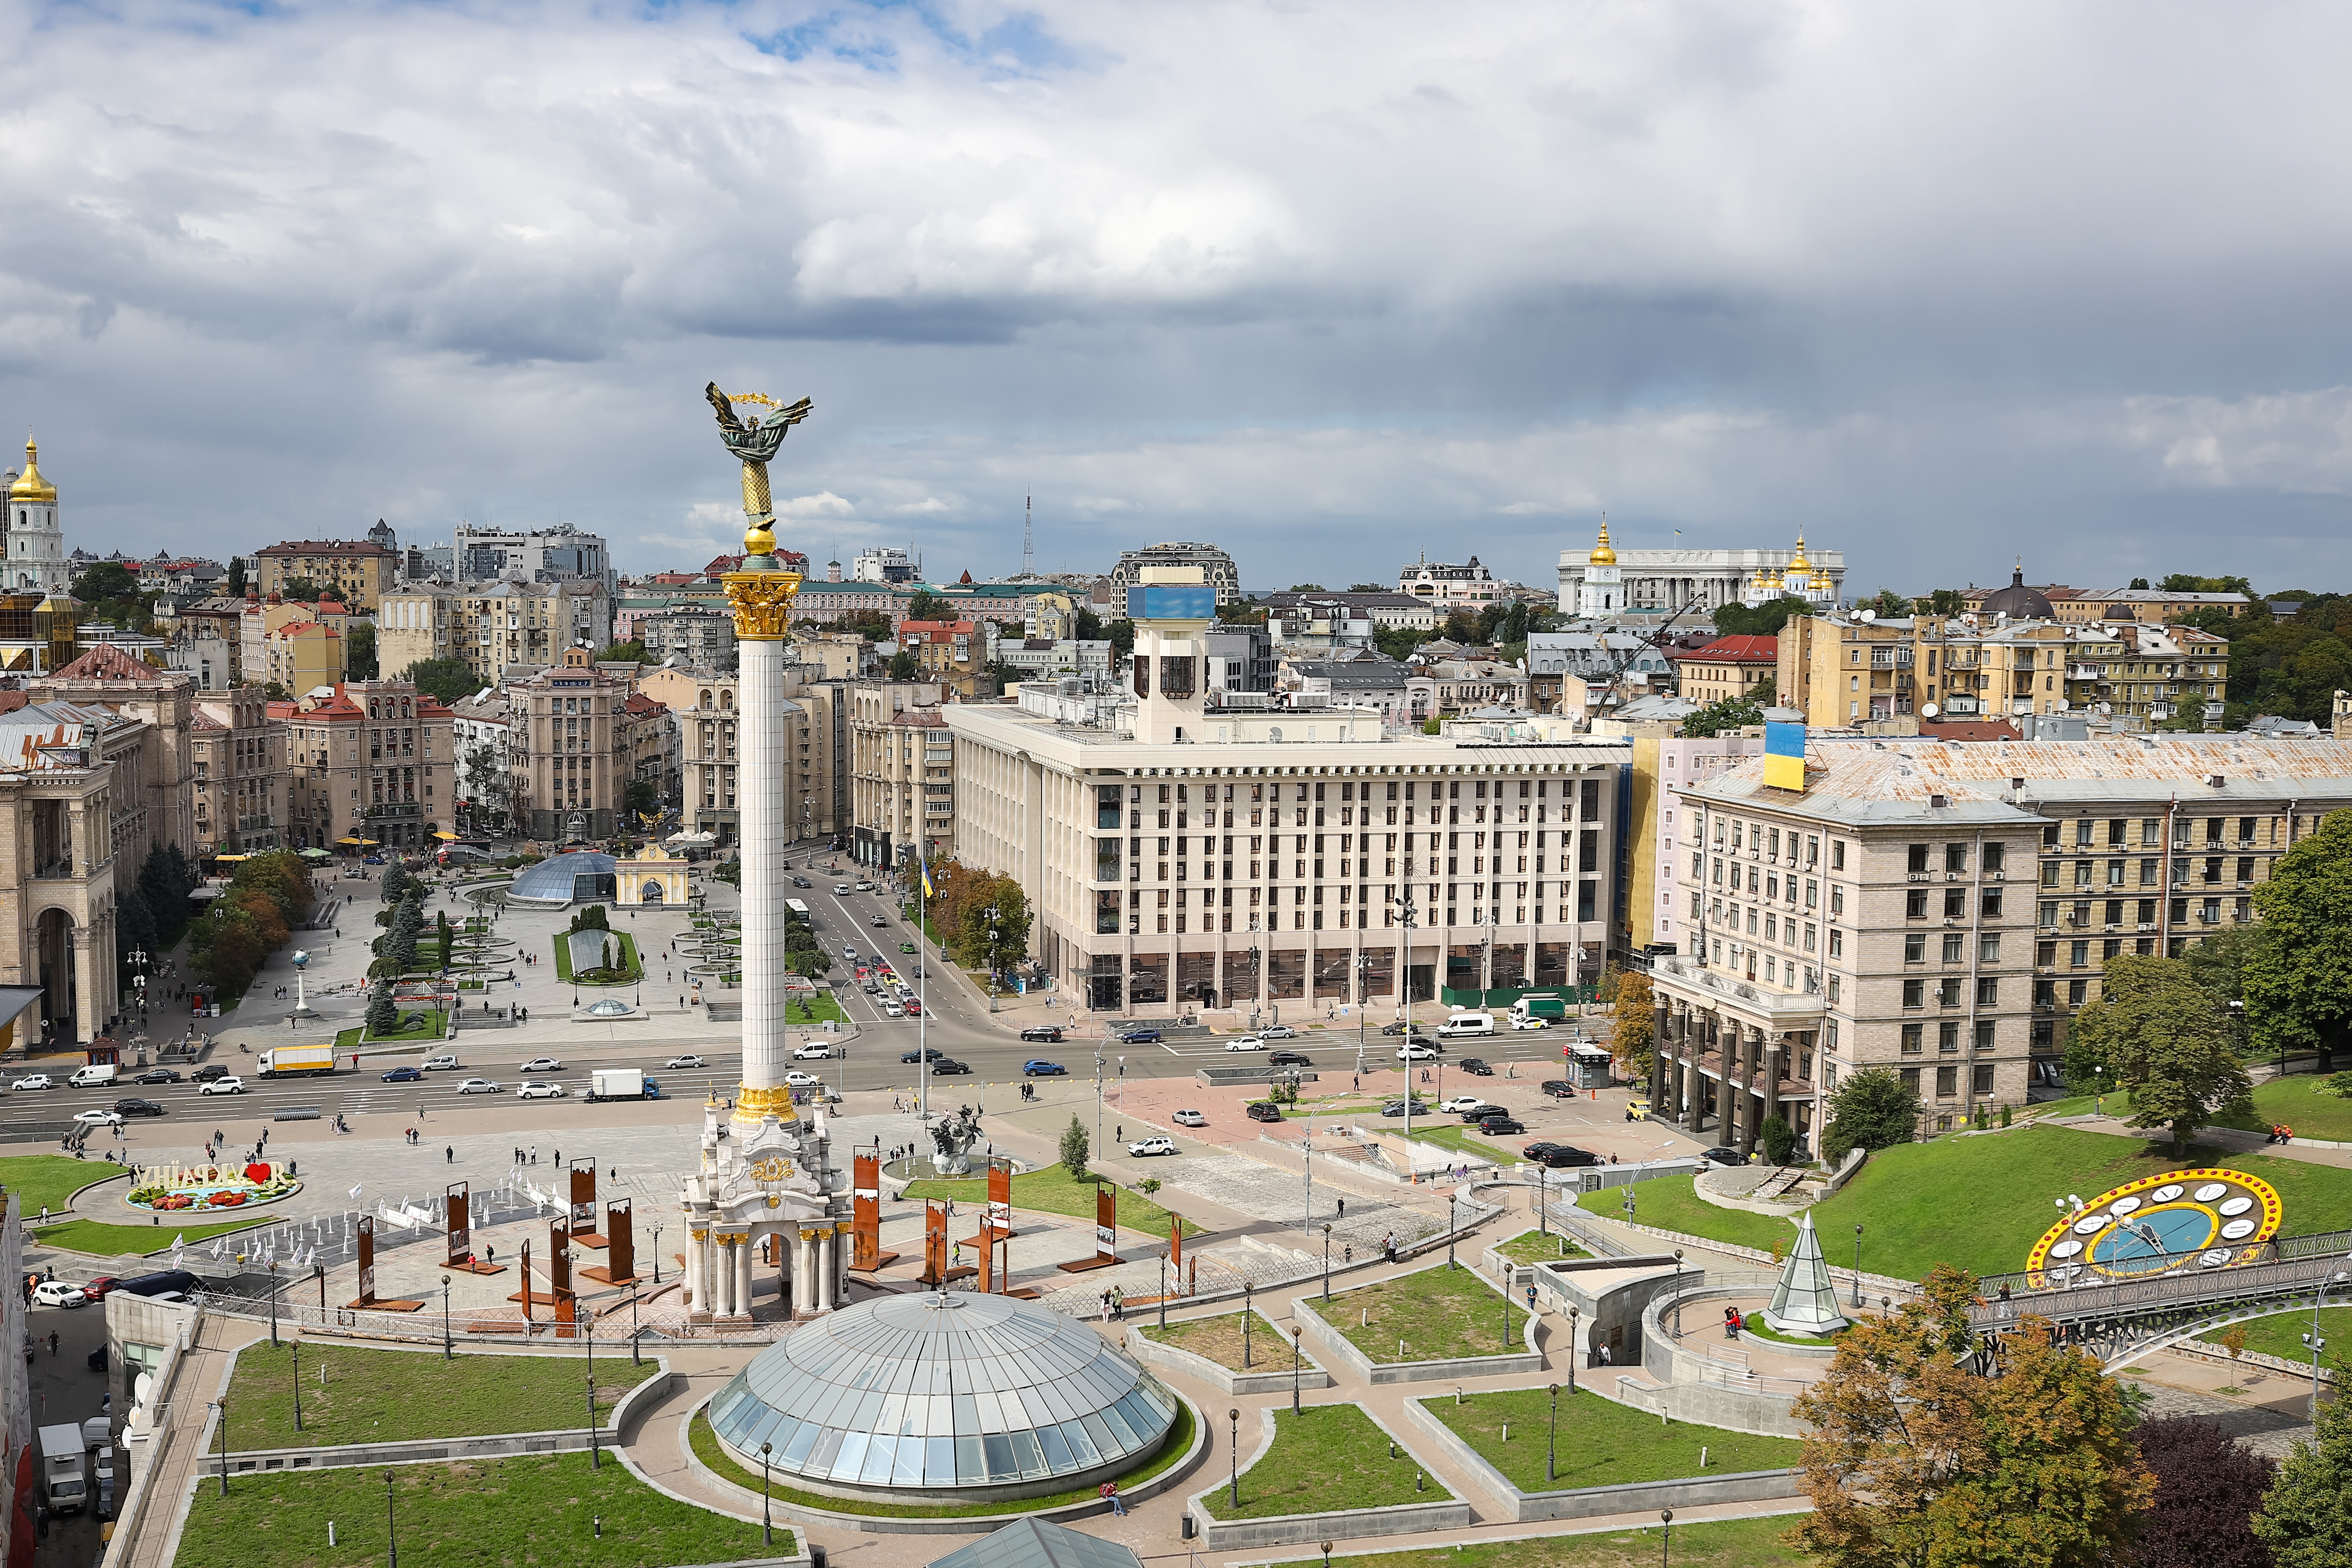
Kyiv Ukraine Cityscape
news

Member Spotlight: Ulysses, Ukraine

By Globalaw, 22 Mar 2026

When a law firm consistently wins over 95% of its cases, people take notice.

Ulysses, an independent law firm based in Kyiv, Ukraine, operates at the intersection of global legal systems to help national and multinational clients reach their goals in high-stakes disputes, public policy issues and complex transactions.

Known for precision, agility, and strategic depth, Ulysses lawyers skillfully apply both domestic and international law, as well as dispute-resolution mechanisms, to deliver effective outcomes.

Bold Thinking, Client-First Strategy

Ulysses defines itself through bold, results-driven representation.

Its ethos? “We win disputes. We close deals.”

Clients turn to Ulysses when the stakes are high politically, commercially, or reputationally. Many choose the firm because their legal issues cross borders or involve complex regulatory challenges.

Ulysses’ client relationships showcase its client-first approach. Whether helping a global corporation navigate a multibillion-dollar M&A deal or representing an investor in a dispute involving international banking regulations, Ulysses is known for relentlessly pursuing outcomes that serve the client’s best interests.

Globally Recognized Dispute & Transaction Expertise

Ulysses’ Disputes practice is built around cases that often influence public policy or international relations, including arbitration and alternative dispute resolution, complex litigation, investor-state disputes, and public international law.

The firm’s transactions and regulatory practice supports major commercial activities, including corporate and M&A, banking and finance, regulatory, and taxation for companies like Porsche Ukraine, EnergoGroup, and DPWorld.

The firm’s excellence has been recognized by leading authorities such as Chambers & Partners, IFLR1000, The Legal 500, WWL, and Liga Zakon.

A Leader in International Law

Ulysses is a leading expert in public international law and treaty-based disputes, garnering recognition in national and international media. Perhaps the strongest testament to the firm’s capabilities is its track record in investor-state matters:

Ulysses has negotiated and finalized 75% of publicly known investor–state settlements with Ukraine. These cases often involve delicate diplomatic issues, requiring a combination of legal knowledge, strategic negotiation skills, and a nuanced understanding of governmental processes.

The firm’s cross-border practice supports clients in the United States, the United Kingdom, the Netherlands, and other jurisdictions, advising on financial transactions, navigating regulatory frameworks, or structuring innovative banking services in Ukraine. Its team continuously monitors regulatory shifts, ensures compliance, and helps clients build internal policies and product standards that meet both domestic and international requirements.

Expanding International Capabilities Through Globalaw

Ulysses’ experience in multijurisdictional matters made its 2022 entry into Globalaw a natural step. The firm’s capabilities align seamlessly with the network’s mission: connecting top independent firms to help clients operate effectively across borders.

Through Globalaw, Ulysses has strengthened its ability to serve corporations, public policy stakeholders, and international entities whose matters often span multiple jurisdictions and regulatory frameworks. It allows Ulysses to support clients with deep local knowledge and coordinated global insight.

For more information, visit ulysses.law.

Latest News

press
25 Sep 2026

What Goes Around, Comes Around: Where We See Opportunity in U.S. Real Estate

For international businesses and investors looking at the United States, the 2026 real estate market offers both surprises and interesting opportunities.

Start with retail, perhaps the biggest surprise of all. Not long ago, conventional wisdom held that e-commerce and the pandemic might spell the end of the American shopping mall. Instead, their values increased approximately 13% over the past year, making malls the best-performing major commercial real estate sector.

Part of the explanation is simple: very little new retail has been built, and available “good” space is tight. But retail itself is also changing. Successful properties increasingly combine traditional stores with restaurants, grocery, fitness, entertainment, and services. Many mall properties are also becoming true mixed-use destinations, adding residential, office, and hospitality use to create “live, work, stay, play” environments. Younger Americans are contributing to the resurgence as well, with consumers ages 18 to 24 making a surprisingly large percentage of their purchases in “brick-and-mortar” stores.

Another interesting trend is “medtail”—the convergence of healthcare and retail real estate. Patients increasingly expect more immediate and convenient access to healthcare services, closer to where they live, work, and shop. In response, urgent care, primary care, imaging, physical therapy, and other outpatient services are opening in shopping centers and other retail locations. Healthcare providers gain visibility, parking, and convenient access to patients, while property owners gain service-oriented tenants that generate regular foot traffic. For healthcare companies, retailers, and investors considering U.S. expansion, that convergence presents interesting opportunities.

The office market is also showing opportunities to maximize investment. Remote work continues to reshape the market as corporations take different approaches to office space use and configurations, with many favoring newer, amenity-rich buildings. This creates opportunities to reposition and redevelop older properties. In many U.S. cities, obsolete office buildings are being renovated to provide the modern, flexible spaces tenants are seeking, while other office buildings are being converted to multifamily apartments. In addition to location and cost, residential conversions require a detailed review of zoning, lease restrictions, suitability of building floor plates and windows, life safety and building codes, and adaptability of existing plumbing and HVAC.

That leads directly to another key sector: housing. The United States remains significantly undersupplied, with zoning, entitlement delays, construction costs, and access to financing often dictating development. Increasingly, the availability of water and sewer is driving where, and whether, new housing projects can get off the ground. For international developers and investors, understanding and navigating local approvals and infrastructure constraints is critical.

Lastly, AI. Data centers have become one of America’s fastest-growing real estate sectors, but the critical constraint increasingly is not land, but electricity. Power availability, transmission capacity, water, and infrastructure are determining where major investments can occur. At the same time, data centers have become controversial in many states, as communities grapple with their enormous power demands, water use, environmental impacts, and effects on surrounding communities.

Key Takeaways

  • Scarcity creates opportunity.
  • Preserve flexibility—the best use of a property tomorrow may not be its use today. Entitlements create value.
  • Infrastructure matters.
  • Real estate is a long-term play.
  • Access to capital is key.

For international companies entering or expanding in the United States, success requires understanding the real estate and the business, regulatory, and infrastructure environment surrounding it.

For more information, contact:

Image

John H. Sokul Jr., Partner

Hinckley Allen

Hinckley Allen’s Real Estate attorneys work closely with the firm’s Retail, Construction, Corporate, and Healthcare practices to assist U.S. and international clients with acquisitions, development, leasing, land use, financing, and opportunities at the intersection of these industries.

news
23 Sep 2026

Globalaw Announces Strategic Relationship with MDD Forensic Accountants

Globalaw announces a new strategic relationship with MDD Forensic Accountants, a leading global forensic accounting firm, providing litigation support services and expert witness testimony in courts and arbitrations. Through this collaboration, Globalaw member firms gain exclusive access to complementary capabilities and expertise that enhance their services and help deliver better client outcomes.

“We are intentional about collaborating with trusted experts who share our commitment to high quality and exceptional service,” said Globalaw Executive Director Ángela López Molina. “With professionals in over 40 worldwide offices who speak over 30 languages, MDD’s expertise strengthens the support our member firms provide to their clients on a local and international basis.”

Strategic relationships reinforce Globalaw’s commitment to giving member firms a distinct competitive edge through access to the innovative tools, resources and technology associated with large global firms. Earlier this year, Globalaw formed a first-of-its-kind global collaboration with Legora, providing members with exclusive access to leading-edge AI solutions. The network also has a long-standing strategic relationship with the AESIS Network, an international network of insurance brokerage and consulting firms based in the Netherlands, with over 75 offices worldwide.

About Globalaw

Founded in 1994, Globalaw is a Band 1 Chambers-ranked global network of approximately 80 independent law firms and 4,000 lawyers in more than 60 countries. Our mission is to foster seamless legal collaboration among member firms and help them deliver high-quality, cost-effective solutions to clients worldwide. We take pride in our commitment to excellence, global reach and innovative approach to legal services. Visit www.globalaw.net to learn more.

Media Contact:

Jaime Luckey

marketing@globalaw.net

news
13 Aug 2026

Indonesian Member Firm Enters Strategic Agreement with Ministry of Youth & Sports

Globalaw is pleased to announce that its Indonesian member firm, Bagus Enrico & Partners, has entered into a Strategic Partnership Agreement with the Ministry of Youth and Sports of the Republic of Indonesia (Kemenpora RI).

"This is a significant milestone not only for Bagus Enrico & Partners but also for the broader development of sports law in Indonesia and the work of Globalaw's Sports Law Taskforce," said Jonathan Cheong, Co-Chairman of the Globalaw Sports Law Taskforce. "It creates a meaningful bridge between Indonesia's sporting institutions and the international legal community and provides an opportunity to further connect Indonesian sport with Globalaw's international network,"

Through Globalaw's international network of sports law practitioners, this partnership can help drive cross-border knowledge exchange, international collaboration, and access to specialised legal expertise, while bringing Indonesia's sporting opportunities and perspectives onto the global stage.

About the Globalaw Sports Law Taskforce

Globalaw’s Sports Law Taskforce is a dedicated advisory group offering specialized legal counsel and representation for athletes and stakeholders across all areas of sports law. From negotiating and drafting athlete contracts, sponsorship agreements, and marketing deals to providing expert counsel on intellectual property rights, endorsements, tax advice and dispute resolution, our cross-border advisory group is equipped to handle all legal aspects of the sports industry, ensuring that our clients receive top-tier support and protection in their careers and business ventures. Learn more about Globalaw's sports law capabilties.

press
07 Aug 2026

Tax Disputes in Italy: A Guide

This summary outlines how tax disputes arise and proceed in Italy, covering the self-assessment system and taxpayer registration, how the tax authority reviews and challenges returns, the treatment of tax fraud, the conduct of audits, options for resolving disputes before litigation, the appeal process through the tax courts, and the penalties and areas of dispute taxpayers are most likely to encounter.

Tax Registration

In Italy, every individual and legal entity receives a tax identification number. Legal entities and partnerships are always assigned a VAT number, while individuals receive one only if they engage in business or self-employment activities, not for salaried employment. Once a taxpayer holds a VAT number, the tax authority is fully aware of that person's existence and economic activity.

Self-Assessment and Amending Returns

The Italian system operates on self-assessment: taxpayers prepare and file their own annual returns, and the tax authority has five years from the following year to review the return and challenge any errors or omissions. A late challenge is null and void, though the taxpayer must still formally seek its annulment through an administrative appeal or legal action.

Returns may be amended to report higher income at any time before an assessment notice is served, substantially reducing potential penalties, or amended to report lower income, subject to specific time limits.

Assessment Notices and Time Limits

The tax authority must issue a reasoned assessment notice that sets out the factual and legal grounds for the challenge, which provision was violated and why, and separately justify any related penalties. In principle, notices must be issued within five years of the filing year (a 2025 return can be assessed until December 31, 2031).

Notices issued later can still be challenged: the taxpayer files a self-protection request for annulment and, failing that, a formal appeal within 60 days, citing the expiration of the deadline.

Tax Fraud

Tax fraud is a criminal, not an administrative, matter, defined by two articles of criminal tax law that cover the use of false invoices (documents recording costs for services never rendered) and other deceptive practices intended to mislead the authorities. It is punished severely, and if charges are filed, the deadlines for serving assessment notices are doubled. It is particularly relevant internationally—for instance, regarding management fees, where Italian companies can struggle to obtain precise supporting documentation for intercompany services. Fraud investigations are conducted by the local public prosecutor, assisted by the Guardia di Finanza under the Code of Criminal Procedure, and may involve restrictions on personal liberty and the seizure of assets. Tax and criminal proceedings run in parallel and both require careful handling

Audit Conduct and Standards

There is no formal code of conduct for audits beyond a general duty of fair cooperation. The Guardia di Finanza has issued a manual outlining audit procedures, and taxpayer rights are set out in the Taxpayer's Charter. Audit reports must invite the taxpayer to provide documentation, note the right to be assisted by a tax lawyer or Chartered Accountant, and state that withheld documentation cannot later be used in court. Audits now typically focus on three main risk areas for multinationals: transfer pricing, interest/dividend/royalty payments and beneficial ownership, and intercompany services.

During audits, inspectors may request any relevant documents, including those from foreign subsidiaries via international information exchange; a refusal generally bars later use of those documents in court. Requests to third parties to cross-check data (e.g., verifying that invoices were recorded by the issuer) are also routinely permitted.

Pre-Litigation Settlement Options

Before litigation, taxpayers have three main options: accept the audit report and pay in full to secure a significant penalty reduction; take voluntary corrective action on specific issues; or negotiate a settlement with the tax authority ("accertamento con adesione"). If none of these options succeed, the only remaining route is the courts, where judicial settlement may still be attempted. The audit relationship is governed by the Taxpayer's Bill of Rights; taxpayers should always respond carefully and in writing. Auditors may remain on the taxpayer's premises for up to 30 days (extendable to 60), though in practice the overall audit, including off-site document review, often takes three to four months.

The Appeal Process

A taxpayer has 60 days from the date of service of an assessment notice to appeal, first to the Revenue Agency that issued it and then, within 30 days, to the Tax Court of First Instance. The appeal must include all arguments at the outset, as further objections cannot be added later. First-instance hearings in Milan take about nine months; the losing party may then appeal to the Second-Instance Tax Court and, finally, to the Court of Cassation, which reviews only legal principles and the soundness of reasoning.

The Tax Court is an independent judicial body covering all tax and related charges. Hearings and judgments are public, and Court of Cassation decisions are published on its website. The procedure is mainly written, with only brief oral argument; the appeal must concisely set out procedural and substantive objections, which may later be clarified—but not expanded—in further briefs. Written documentary evidence is admissible; witness testimony is not generally central, though it can matter in specific disputes, such as demonstrating non-payment.

Burden of Proof

On the burden of proof: the tax authority must justify its challenge in detail (e.g., explaining why an expense should not be considered business-related), while the taxpayer must substantiate the item's legitimacy and show that the authority's findings are unreasonable; the authority cannot rely on generic, unsupported challenges.

Duration and Payment Obligations

Proceedings can be lengthy—up to about 12 years from assessment to a Court of Cassation decision in complex cases. Upon assessment, taxpayers must pay one-third of the additional tax claimed; a stay of payment is possible but difficult to obtain, requiring both urgency (periculum in mora) and a reasonable likelihood of success (fumus boni iuris), and is particularly hard to secure for large corporations, banks, or insurers.

Representation, Costs, and Alternative Dispute Resolution

Representation before the first two levels of the tax courts must be by qualified professionals, and for cassation proceedings, by an attorney qualified before the Court of Cassation. It is advisable to use a Chartered Accountant and a tax lawyer together. The losing party generally bears the costs of the proceedings. There are two levels of tax adjudication before the Court of Cassation.

For international disputes, particularly transfer pricing, arbitration (conventional or EU) is available to avoid double taxation. Purely domestic disputes have no alternative to litigation apart from mechanisms like "accertamento con adesione."

Penalties

Penalties for additional assessed tax are generally 70% of the tax due, plus interest. Penalties may be mitigated or waived in cases of objective legal uncertainty, assessed on a case-by-case basis; for transfer pricing specifically, penalties can be avoided by preparing appropriate documentation in advance.

Outlook

Looking ahead, the main areas expected to generate disputes are tax avoidance (abuse of right), transfer pricing, and beneficial ownership. No single area is seen as uniquely difficult, though the relationship with tax authorities remains complex: local offices are sometimes aggressive, rely on one-sided ministerial circular interpretations while disregarding contrary case law, and case law itself is not always fully consistent.

For more information, contact:
Image

Paolo Comuzzi, Partner

Lawal Legal & Tax Advisory